All Categories
Featured
Table of Contents
How Does LendingTree Get Paid? LendingTree is compensated by companies whose listings appear on this site. This settlement might affect how and where listings appear (such as the order or which listings are featured). This site does not consist of all companies or products offered. We are committed to supplying precise content that assists you make notified money decisions.
Read our editorial guidelines here. Americans have a record amount of credit card debt $1.252 trillion, to be specific. This charge card financial obligation stats page tracks Americans' charge card utilize each month. We upgrade this page routinely, taking a look at how much debt customers hold, how typically they carry balances from month to month, how regularly they pay their charge card bills late and other essential patterns.
While credit card debt tends to increase year over year, it generally falls from Q4 of one year to Q1 of the next. Even with this quarter's reduction, credit card balances have actually risen by $482 billion considering that Q1 2021, when credit card debt bottomed out at $770 billion during the pandemic.
Americans' charge card financial obligation is $325 billion greater than the pre-pandemic record embeded in Q4 2019, when balances stood at $927 billion. (That's a 35% increase.) Credit card balances have actually historically rebounded after first-quarter declines, though future borrowing trends will depend on factors consisting of rates of interest, inflation and more comprehensive economic conditions.
Best Debt Management Strategies to Eliminate Debt
Charge card financial obligation rose progressively until the financial crisis, then declined from $866 billion in Q4 2008 to $660 billion in Q1 2013 before resuming its upward trajectory. When the pandemic took hold in 2020, credit card balances plunged once again from $927 billion in Q4 2019 to $770 billion in Q1 2021.
Credit cardholders in Connecticut have the greatest average charge card financial obligation of any state, according to LendingTree information, while those in Mississippi have the most affordable. Source: LendingTree analysis of the anonymized credit reports of more than 400,000 LendingTree users in the third quarter of 2025 and more than 410,000 in Q3 2024.
Joint accounts were divided in half to show shared duty in between the account holders. LendingTree experts evaluated anonymized credit report information from Q3 2025 for more than 400,000 LendingTree users to determine these averages and create a list of states with the most financial obligation. The analysis was also compared with Q3 2024 data from more than 410,000 reports.
Key Strategies for Financial Stability in 2026Eleven states had average balances of at least $9,000. Connecticut leads at $9,778, ahead of New Jersey ($ 9,748) and Maryland ($ 9,630). The 6 states with the most affordable balances are in the South. Mississippi's balance is $4,887, lower than Arkansas ($ 5,259) and West Virginia ($ 5,336). Washington has the fastest-growing card financial obligation in the period analyzed.
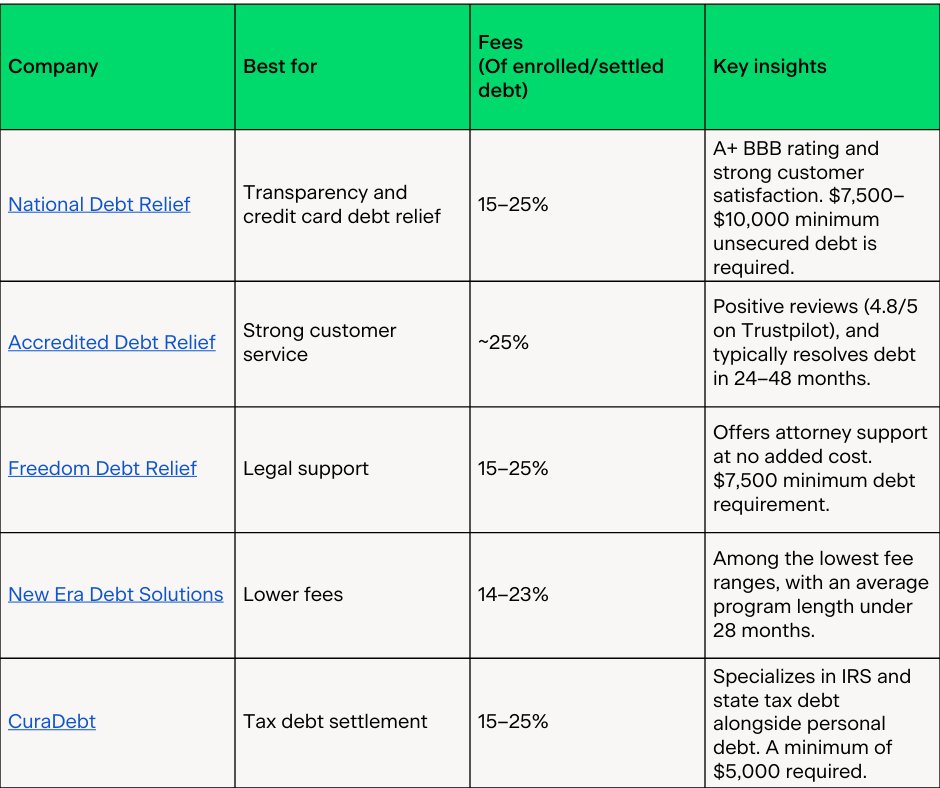
Analyzing the Top 2026 Debt Relief Options
3 other states saw double-digit boosts, including South Dakota (up 11.7%), Nebraska (up 11.3%) and Wisconsin (up 10.2%). On The Other Hand, New Mexico saw the biggest year-over-year decline in debt, with its citizens' debt falling 10.3% from $6,543 to $5,871. In all, seven states saw credit card balances decrease in the past year.
Less than half of adult credit cardholders (45%) brought a balance on a charge card for a minimum of one month in the past year, according to a May 2026 Federal Reserve study utilizing 2025 data. Paying a credit card balance completely each month is the most effective way to avoid interest charges and keep debt from building up.
Key Strategies for Financial Stability in 2026For cards accruing interest, the average in Q2 2026 was 22.15%. For brand-new credit card offers, the average is 23.79%.
Consumers opening a new charge card account might face higher rates than the averages for existing accounts. The most recent LendingTree information on charge card APRs shows that the typical APR with a brand-new charge card deal is 23.79%, with the typical card offering an APR variety of 20.18% to 27.41%.
The 23.79% average was unchanged for the 2nd straight month and 3rd in four. It's the first time considering that LendingTree started tracking card rates regular monthly that they went the same in back-to-back months. That stability is likely the result of the Fed leaving rates the same throughout 2026. When the Fed raises or reduces rates, the majority of credit card APRs in the U.S.No matter when the Fed acts next, any motion is likely to be little, suggesting charge card APRs would likely remain raised by historical standards. And as the chart listed below programs, APRs can vary significantly by card type. Source: LendingTree review of publicly available conditions for about 220 U.S.Obviously, your best move is to make those interest rates a moot point by paying your card financial obligation completely, however that's often much easier said than done. Just 2.92% of Americans' outstanding charge card balances were at least 1 month overdue in the very first quarter of 2026. According to the most current delinquency information from the Fed, the 30-day delinquency rate the share of outstanding charge card balances that were at least 30 days overdue dipped to 2.92% in the very first quarter of 2026, the seventh straight quarterly decrease.

Latest Posts
Optimizing Debt Relief Strategies in 2026
Ways to Navigate Financial Hardship in 2026
Professional Analysis of 2026 Debt Relief Trends