All Categories
Featured
Economists recommend that anybody thinking about charge card debt forgiveness initially evaluate their monetary situation, communicate directly with their financial institution or a trustworthy counseling service, and understand both the short-term and long-term effects. With mindful preparation and confirmation, eligible Americans can take benefit of these programs in 2026 to decrease financial stress and pursue long-lasting monetary stability.
Effective Strategies to Handle Over-Leveraged Debt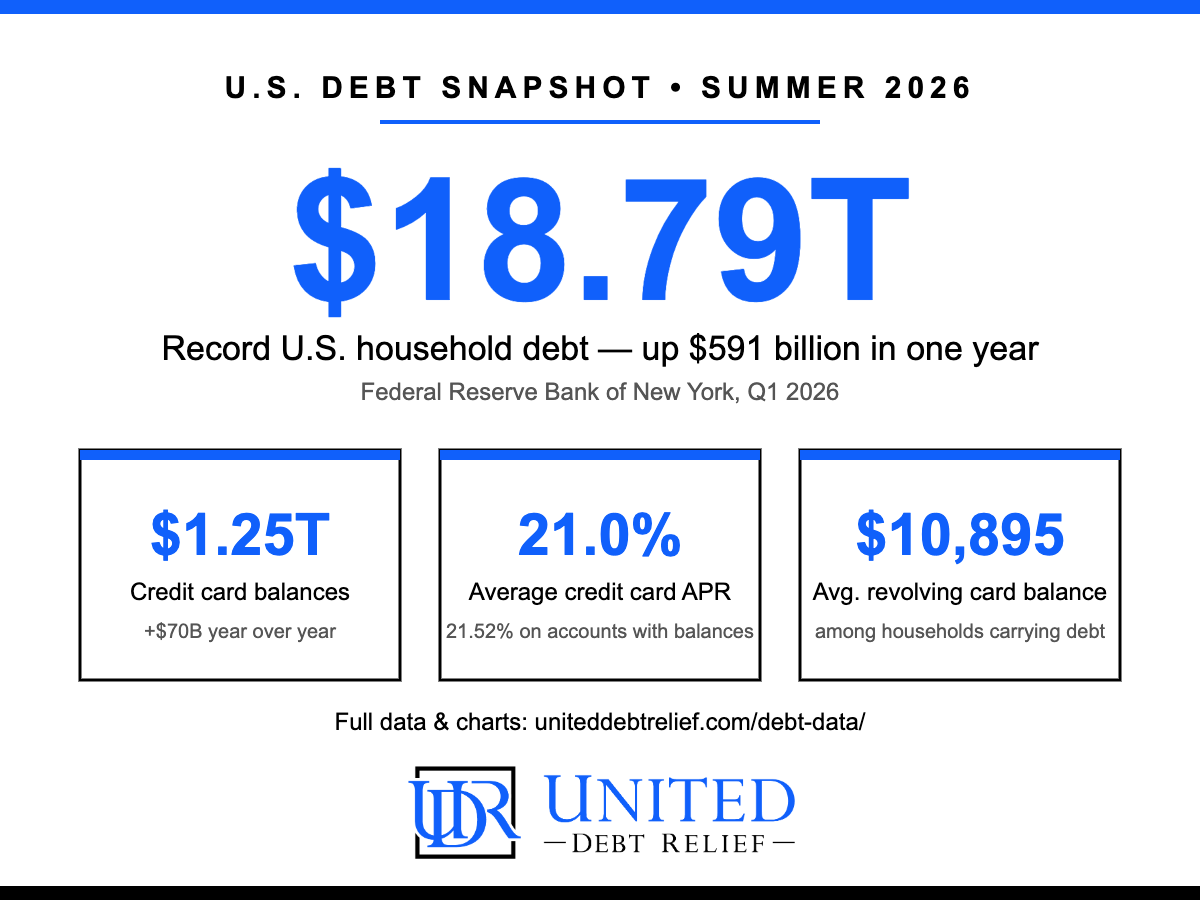
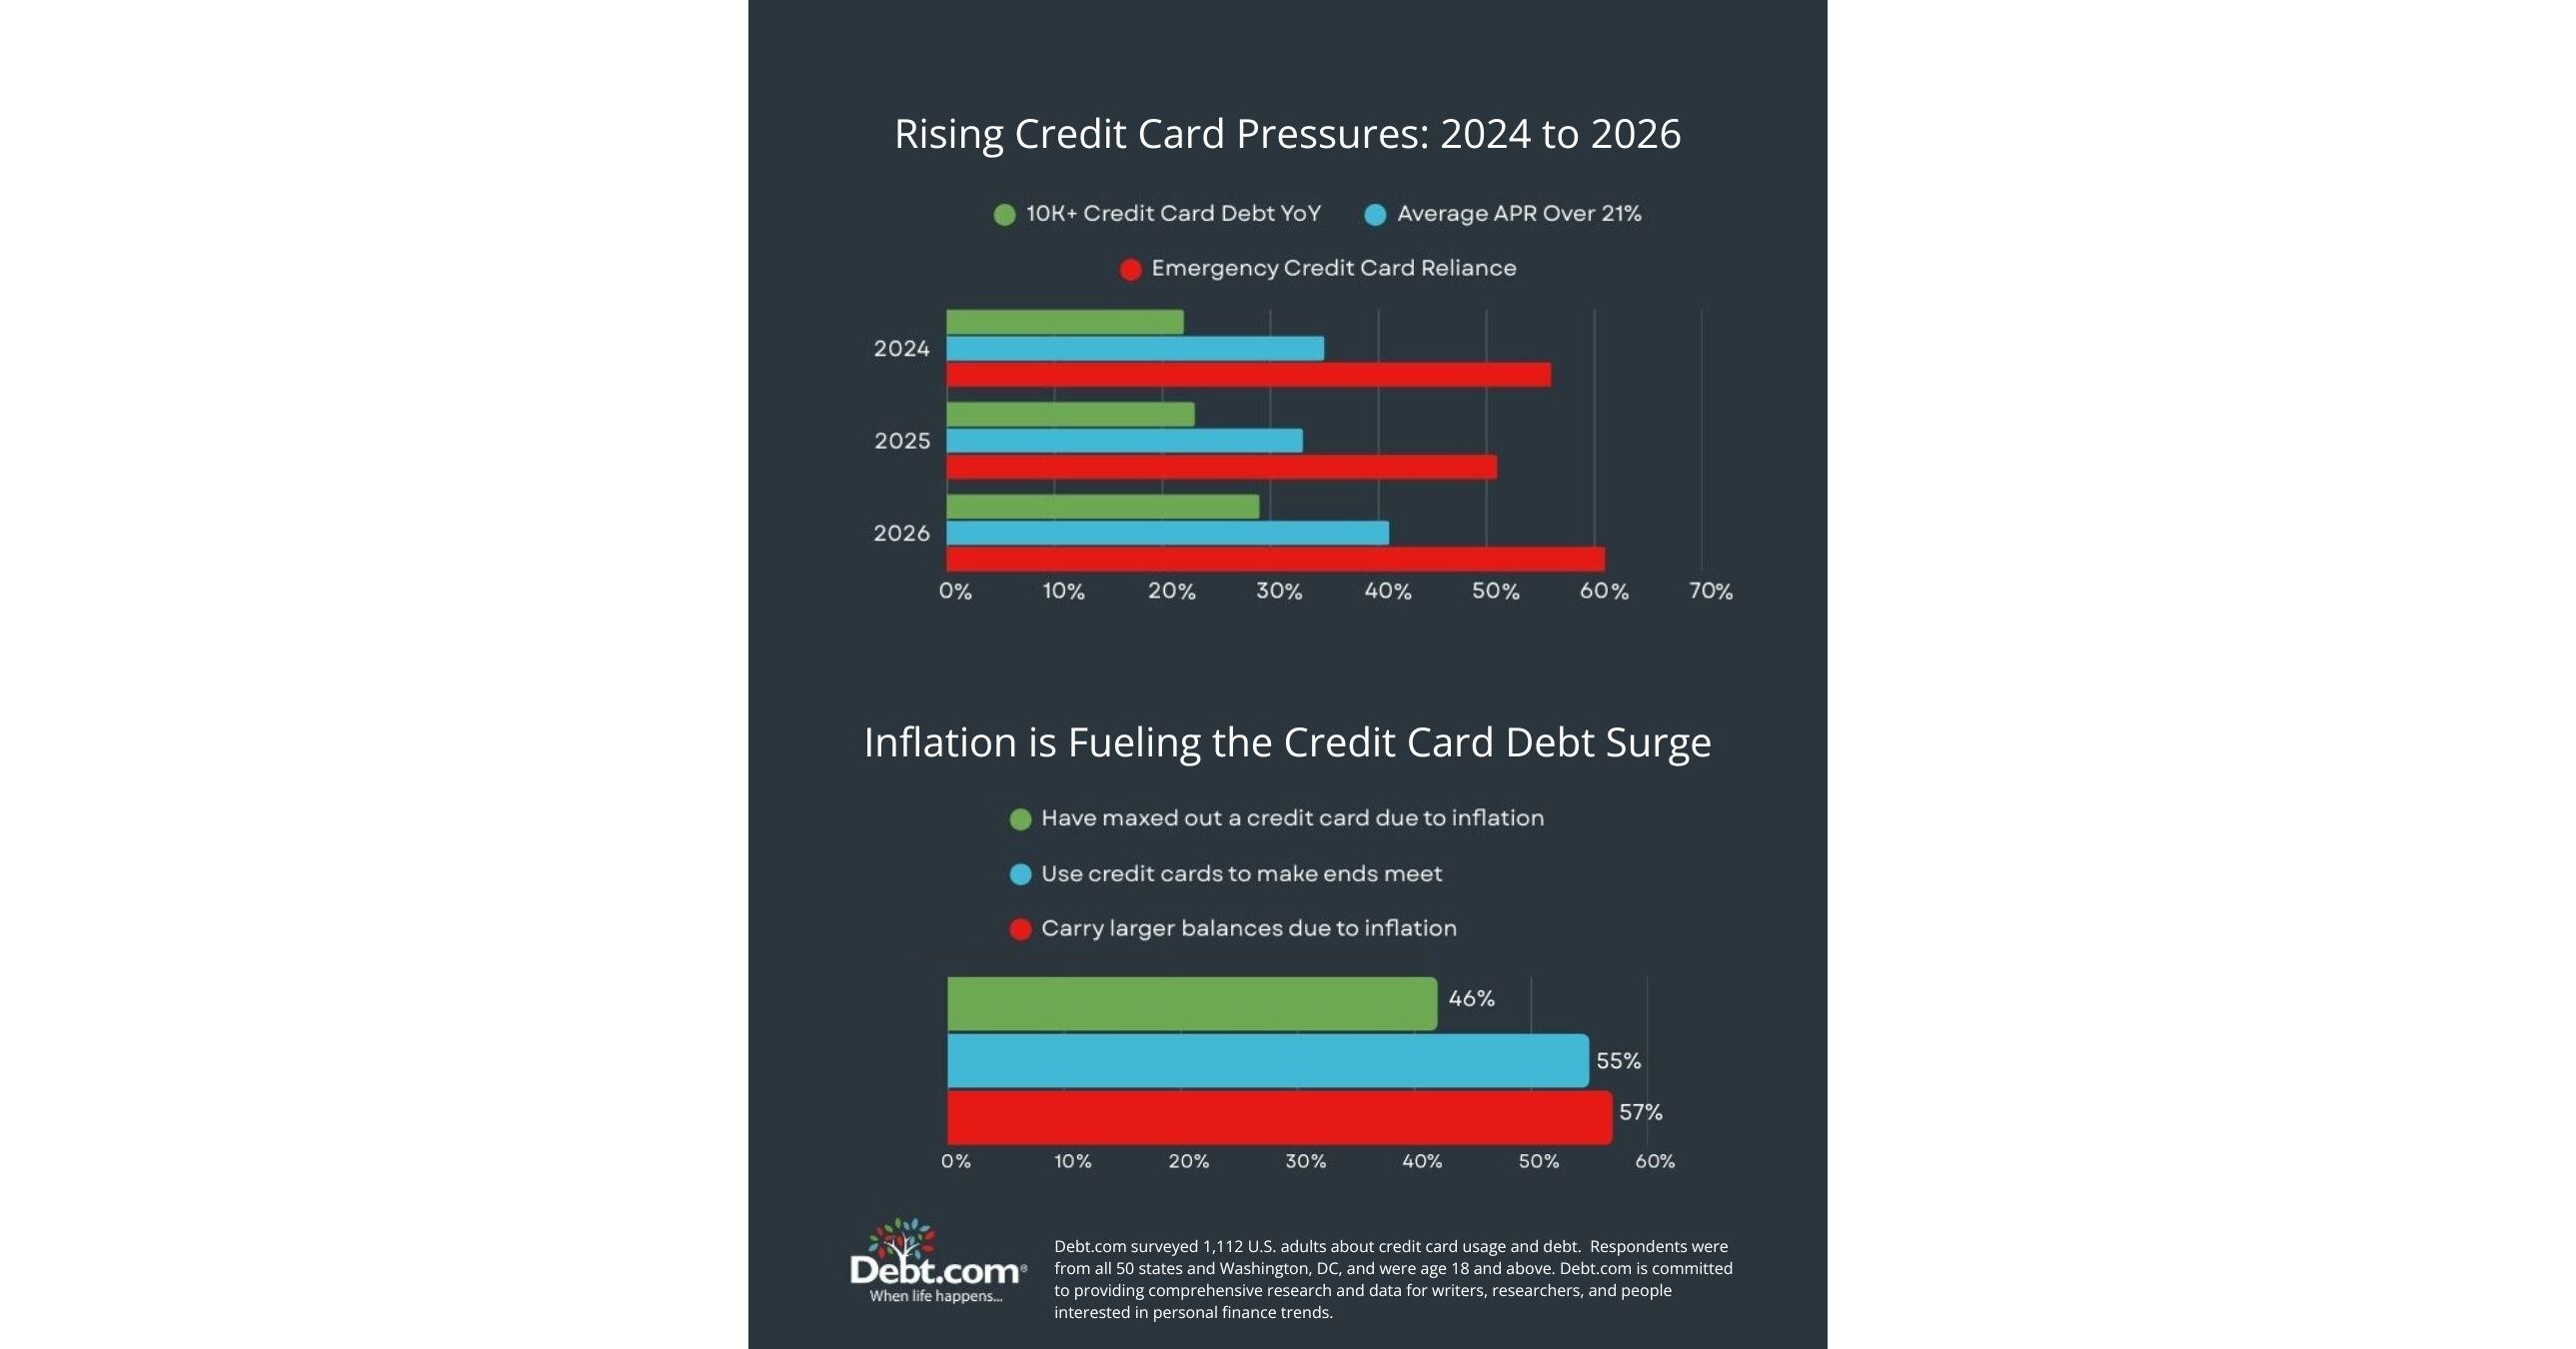
Here are the legitimate financial obligation relief programs that rank highestand how to decide between settlement and credit counseling. Not all debt relief programs fit all circumstances. Here's how to inform which one matches your challenge level: Financial obligation consolidation loanNonePay 100%, better termsGood credit, steady earnings, simply need to simplifyCredit therapy (DMP)Mild/ModeratePay 100%, lower interestCurrent on payments, can pay for decreased ratesDebt settlementSignificantPay less than 100%Already behind, can't manage minimumsBankruptcySevereLegal discharge/restructureOverwhelmed, creditors taking legal action against, no other alternative You're already behind on payments by 90+ daysYou can't pay for minimum payments even with lower interestYou're facing considerable financial challenge (task loss, medical emergency situation, divorce)Your credit is currently damaged from missed paymentsYou can conserve $200-$500/month toward settlements You're existing on payments or only a little behindYou have constant earnings to cover a regular monthly paymentYou want to prevent major credit damageYou can manage to pay back 100% if interest is loweredYou require 3-5 years to pay off debt Ask yourself: Can I manage my minimum payments if interest rates were cut to 0-8%?

Latest Posts
Optimizing Debt Relief Strategies in 2026
Ways to Navigate Financial Hardship in 2026
Professional Analysis of 2026 Debt Relief Trends