All Categories
Featured
When the balance has actually reached an adequate level, NDR negotiates with your specific lenders in an attempt to get them to accept less than what is owed. If a settlement is reached, the debt is paid from the escrow account. FEES: 15%-25% of the original financial obligation. The company site does not note any other charges.
CREDIT RATING IMPACT: It's a substantial negative and it lasts for 7 years. Expect your credit report to drop 75-125 points as your bills go overdue and accounts end up being overdue. There are numerous avenues to removing financial obligation through financial obligation consolidation, but there are just as numerous detours that will intensify your issue if you are not paying attention.

There are a lot of advertisements in this industry that sound too good to be true and it's because they are! Don't fall for them. The first thing to take a look at before signing up with a financial obligation combination program is confidence that the agency, bank, credit union or online lending institution exists to assist you, not to make money off you.
So, if the fees charged make it a break-even exchange, there actually is no reason to sign up. Your total cost in a program must conserve you money while eliminating your financial obligation. Credit combination companies work by discovering an inexpensive way for customers to pay off credit card financial obligation and still have enough cash to meet the cost of fundamental needs like housing, food, clothes and transport.
They vary from giant nationwide banks to small not-for-profit therapy agencies, with a number of stops in between and provide numerous types of credit card financial obligation relief. To streamline things, it is most convenient to divide credit debt consolidation companies into two classifications: Those who consolidate debt with a loan based on your credit report Those who combine financial obligation without a loan and don't use a credit rating at all Banks, credit unions, online lenders and credit card companies fall under the first group.
Will Credit Management Improve Your Financial Future?
They start by evaluating your earnings, expenses and credit score to identify how creditworthy you are. Your credit score is the key number in that equation.
InCharge credit therapists take a look at your earnings and costs, but do not take the credit history into account, when examining whether you receive a debt management program. Based on the details provided, they suggest debt relief options such as a debt management program, financial obligation consolidation loan, debt settlement or applying for bankruptcy as possible solutions.
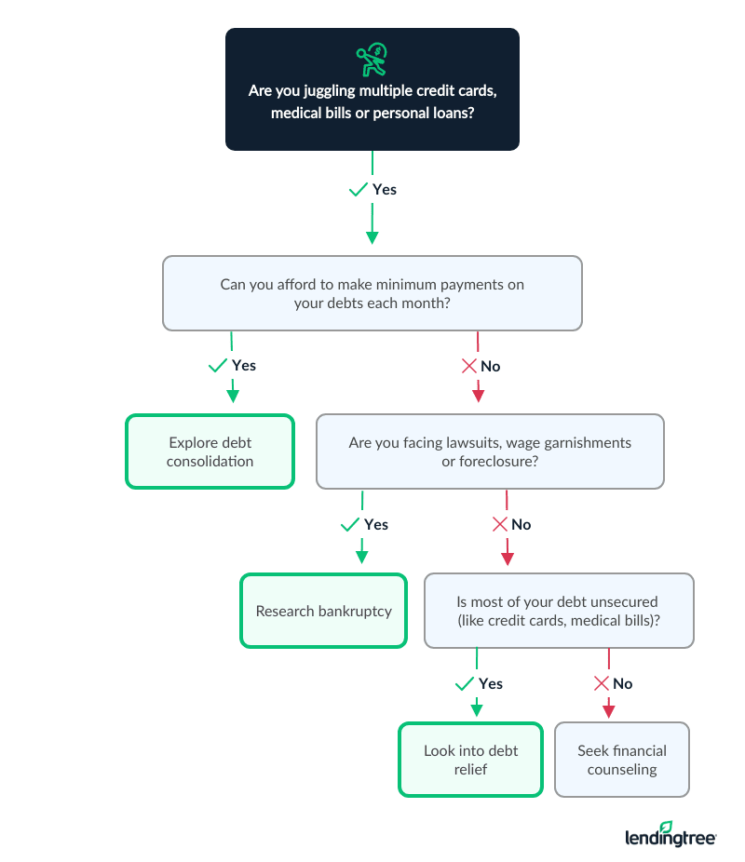
If you have adequate income to pay your costs, nonprofit debt combination works. You can cancel any time and still have the other programs readily available as choices.

Latest Posts
Optimizing Debt Relief Strategies in 2026
Ways to Navigate Financial Hardship in 2026
Professional Analysis of 2026 Debt Relief Trends